The Rise of FinTech Startups: How They’re Disrupting Financial Services
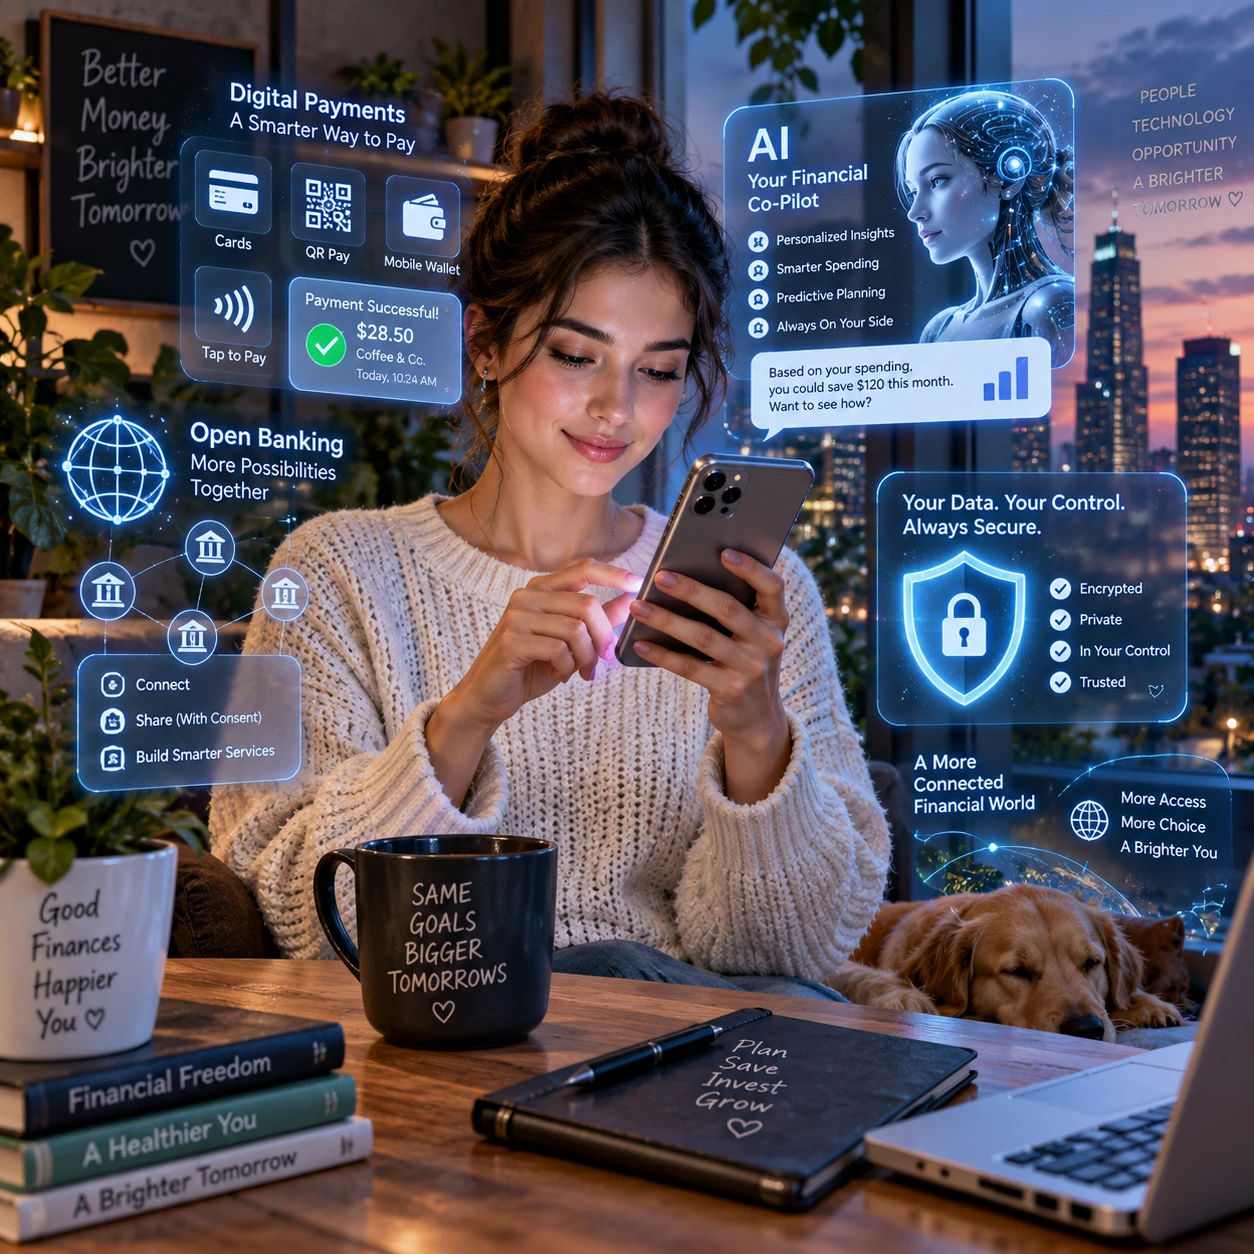
FinTech startups are changing how people pay, borrow, save, and manage money. By combining software with financial services, they can offer digital-first experiences that are often faster and easier to use than older processes. Their growth is reshaping competition, but it does not mean traditional banks will disappear.
The shift is better understood as a mix of competition and collaboration. Startups bring focused products and rapid experimentation; established institutions contribute capital, infrastructure, regulatory experience, and customer relationships. How well these groups serve people depends on technology, sound business models, consumer protection, and trust.
What FinTech startups are and why they’re growing
FinTech startups are young companies that use technology to deliver or improve financial products and services. Their growth reflects wider digital access, rising expectations for convenient service, and tools that make it easier to build financial products online.
The term covers a broad range of businesses: a mobile payments provider, an online lender, a neobank, or a personal finance app may all be described as FinTech. They do not necessarily hold a bank charter or perform every part of a financial service themselves. Some partner with banks or other licensed providers to handle deposits, payments, or lending.
Consumers have grown accustomed to managing many everyday tasks through a phone. That expectation has carried into finance: people may want to open an account remotely, see spending updates promptly, or apply for credit without mailing forms. Cloud computing, digital identity tools, and application programming interfaces (APIs) help companies build and connect these services.
Digital access alone does not guarantee success. Startups must still earn customer confidence, make their economics work, and meet applicable rules. A polished app cannot compensate for unclear fees or weak support when something goes wrong.
The financial services they’re transforming
FinTech startups are reshaping payments, lending, banking, and personal finance by moving more steps into digital channels. The changes can make routine services easier to access, though the product and its safeguards matter as much as the app interface.
- Digital payments: Payment apps and online checkout tools let people send money or pay merchants through phones and websites. Their convenience depends on reliable processing, fraud controls, and clear handling of disputes.
- Online lending: Digital lenders collect applications and supporting information online, then assess borrowers using their own underwriting processes. Faster applications can reduce paperwork, but approval speed does not guarantee affordable terms or fair decisions.
- Neobanks: These digital-first providers offer banking services through websites or apps, often with limited or no branch access. Some hold banking licenses; others rely on partner institutions, so customers should understand which company provides each service.
- Personal finance apps: Budgeting, savings, and account-aggregation tools help people view transactions, set goals, or monitor spending. Their usefulness depends on accurate data, appropriate privacy protections, and features that fit the user’s needs.
These categories can overlap. A company may combine payments with a digital account, or offer a budgeting tool alongside lending. That breadth can be convenient, but it can also make it harder to compare prices and identify who is responsible for customer service.
Technology and business models behind the shift
FinTech startups use technologies such as artificial intelligence, blockchain, and open banking to build or connect financial services. The technology is a means to a service, not proof that the service is safer, cheaper, or more effective.
AI, blockchain, and open banking in practice
Artificial intelligence (AI) can help sort customer-service requests, flag unusual transactions, or support credit assessments. These uses may speed up routine work, but models can make errors or reproduce bias in their data. A provider still needs appropriate oversight, testing, and ways to review consequential decisions.
Blockchain is a shared digital record system in which transactions can be recorded across a network. It may support particular payment or settlement arrangements, but it is not required for most FinTech products. A blockchain-based service can still involve operational risks, uncertain regulation, or difficult recovery when users lose access.
Open banking enables customers, with their permission, to share financial data through secure connections between providers. That data can help an app group accounts or offer a more complete view of spending. Permissions should be understandable, limited to a clear purpose, and revocable where the service allows.
Digital-first delivery and revenue
Many startups keep costs down by serving customers online rather than through a large branch network. They may earn revenue from subscriptions, transaction fees, interest on lending, merchant fees, or partnerships. Each model brings trade-offs: a free app may rely on another revenue source, while a subscription may be worthwhile only for customers who use its paid features.
Some digital providers depend on banks or payment networks for regulated functions and infrastructure. That arrangement can help a startup launch, but it creates dependencies. A service’s reliability may be affected by its partners as well as by the startup’s own systems.
Benefits for consumers and businesses
FinTech products can make financial tasks more convenient, speed up some processes, and tailor information to individual needs. They may also reach people who have had limited access to certain services, although access does not automatically mean affordability or fair treatment.
For consumers, a well-designed digital service may reduce paperwork, show account activity in one place, or provide timely alerts. A small business might use online payments or invoicing tools to accept payments and track cash flow without building its own financial systems. These benefits are most useful when the product solves a specific problem and makes its costs easy to understand.
Digital services can also extend access. Remote onboarding may help people who live far from branches or have difficulty attending appointments. Alternative data can sometimes add context to a credit assessment, but users should not assume it will improve their eligibility or terms. Automated systems can exclude people too, especially if they lack reliable internet access, digital identification, or records the system recognizes.
A practical way to assess a product is to check three things: what it helps you do, what it costs, and who is responsible if something fails. If any answer is unclear, compare providers before moving money or sharing account data.
Risks and challenges FinTech startups face
FinTech startups face risks involving data privacy, cybersecurity, consumer protection, regulatory compliance, and public trust. These challenges affect users directly and can also limit a company’s ability to operate or grow.
Financial apps may handle sensitive identity and transaction data, making security controls essential. Account takeovers, phishing, service outages, or mishandled data can cause real harm. Consumers should use strong, unique passwords and available multifactor authentication, while providers need tested security processes and a clear response plan.
Regulatory compliance varies by country, product, and activity. Rules may cover lending, payments, privacy, anti-money-laundering controls, disclosures, and complaints. A startup that moves quickly without understanding which requirements apply can face penalties or be forced to change its product. The U.S. Consumer Financial Protection Bureau, for example, publishes guidance and consumer information about financial products and services at consumerfinance.gov.
Other concerns are less visible at signup. A low introductory fee can rise, a loan’s total cost may be difficult to compare, or an automated decision may be hard to challenge. Before relying on a provider, review its fee schedule, privacy terms, customer support options, and protections for deposits or transactions. These protections differ across products and jurisdictions; a familiar-looking app is not itself a guarantee.
How startups and traditional institutions are responding to each other
FinTech startups and traditional financial institutions compete for customers while also forming partnerships. Startups often bring focused digital products and quicker experimentation; established institutions bring financial infrastructure, regulatory experience, and long-standing customer relationships.
A startup may challenge a bank with a smoother payments or budgeting experience. In other cases, a bank may use a startup’s software, invest in a technology provider, or distribute a partner’s product. Partnerships can help a startup reach customers and meet operational needs, but they can add complexity and dependence on a third party.
Established institutions have advantages that are difficult to reproduce quickly, including large customer bases and experience managing financial operations. They may also face constraints from older technology systems and complex internal processes. Startups can move faster in a narrow area, yet often lack the scale, funding, and risk-management capacity of a major institution.
For customers, the useful question is not simply whether a provider is a startup or a bank. Check which company holds funds, processes payments, makes credit decisions, handles complaints, and provides any applicable protections. The answer may involve more than one organization.
What’s next for FinTech disruption
The next phase of FinTech disruption will likely focus on more connected services, responsible automation, and practical uses of open banking and AI. Progress will depend on whether providers can make these tools reliable, secure, understandable, and compliant.
AI may take on more routine support and data analysis, while open banking connections may make it easier for customers to use financial information across providers. Payments may also become more integrated with online shopping and business software. These are opportunities, not guaranteed outcomes: adoption can stall if customers see little value, data sharing feels risky, or oversight cannot keep pace.
Financial inclusion will remain a key test. Products that reach underserved communities can help, but providers need to account for people with limited connectivity, irregular income, or different accessibility needs. A service should be judged by who can use it, what it costs, and how it treats customers when they need help, not just by how quickly they can sign up.
For consumers and businesses, the steady rule is to evaluate the actual service rather than its technology label. Compare terms, understand who provides each part, and look for clear safeguards. FinTech startups will keep changing financial services, but trust and useful outcomes will determine which changes last.
Frequently asked questions about FinTech startups
What is a FinTech startup?
A FinTech startup is a young company that uses technology to provide or improve a financial service, such as payments, lending, digital banking, or personal finance management.
How do FinTech startups make money?
They may earn money through subscriptions, transaction or merchant fees, lending revenue, or partnerships. The model varies by product, so customers should check how a service is funded and whether charges apply.
Are FinTech startups safe to use?
Safety depends on the provider, product, security practices, and applicable consumer protections. Review the company’s terms, data practices, fees, support options, and the role of any partner institution before using a service.
Do FinTech startups replace traditional banks?
Some compete directly with banks, while others work with them or provide tools that banks use. Traditional institutions continue to play important roles, and the relationship varies across services and markets.